On this page
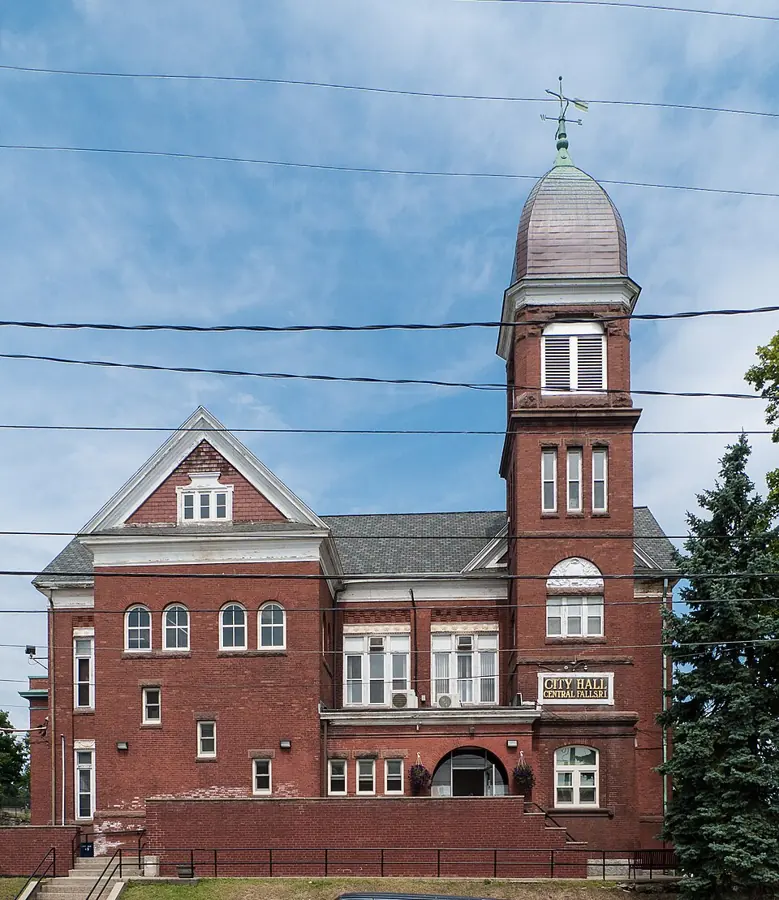

Central Falls Car Insurance When You Don’t Own a Car
If you live in Central Falls and don’t own a car, you can still carry your own auto insurance protection. The two main paths are a non-owner car insurance policy or a standard auto policy, depending on how you actually use vehicles day to day.
This guide is published by RhodeIslandAutoInsurance.com, an independent Rhode Island insurance agency operated by Drivers Insurance Agency, Inc. We help Central Falls residents compare coverage options across multiple carriers-subject to eligibility-but we are not a government office, a state agency, or an insurer. A quote request at /car-insurance-quotes/ or by calling (844) 231-1313 does not bind coverage. Coverage begins only when binding is confirmed and an effective date is established.
Below, you’ll find a practical breakdown of Rhode Island’s minimum liability requirements, how non-owner coverage works under state law, when a standard policy is the better fit, what UM/UIM rules mean for you, and how to compare options specific to Central Falls, RI.
Finally, Central Falls Car Insurance Built for Drivers Without a Car
If you borrow a family member’s car for errands, rent a vehicle for weekend trips, or ride with friends most days but occasionally take the wheel, you may feel unsure about what kind of policy-if any-you actually need.
A common gap in understanding is the assumption that someone else’s auto insurance always covers you completely. In most cases, the vehicle owner’s policy is primary when you drive with permission. But policy definitions control what counts as covered use, and certain situations-like frequent borrowing, using a car not listed on any active policy, or renting-can leave you financially exposed if something goes wrong.
RhodeIslandAutoInsurance.com is a trusted insurance agency focused on helping Central Falls drivers navigate these situations. Whether you have tickets, a prior accident, or a lapse in coverage history, our agents can explore your options across multiple carriers. We can also help when a move, a new home, or business-related insurance needs change what coverage makes sense. We work with Central Falls residents over the phone at (844) 231-1313 or through the /car-insurance-quotes/ page online.
Why the Right Central Falls Car Insurance Strategy Matters
Central Falls is one of the smallest and most densely packed cities in Rhode Island. This guide focuses on people who share vehicles, borrow cars from relatives, use transit, or rent when they need to travel. Insurance rates in densely populated areas tend to be higher due to traffic density, making coverage decisions even more consequential.
Even without owning a car, you may face serious financial exposure if you cause an accident while driving a borrowed or rental vehicle. Bodily injury claims, property damage, and legal costs can quickly exceed what another person’s policy will pay-especially if their limits are at the state minimum.
Coverage decisions in Central Falls must follow Rhode Island insurance regulations, including the state’s minimum liability limits under 230-RICR-20-05-3 and the UM/UIM offering rules in 230-RICR-20-05-1. These aren’t optional guidelines-they define the legal floor for every auto policy issued in the state.
Local incidents reinforce why this matters. The Central Falls Police Department and the Central Falls Fire Department respond to crashes, emergencies, and fire calls regularly-even on short local drives. Accident reports and records are available through the police department’s records page. A single collision on a compact city street can involve pedestrians, parked cars, and significant liability.
The sections that follow compare non-owner policies with standard auto policies, explain Rhode Island liability limits and UM/UIM rules, and show how RhodeIslandAutoInsurance.com can help Central Falls residents make informed decisions.
Why Our Central Falls-Focused Approach Works
RhodeIslandAutoInsurance.com looks at how Central Falls residents actually use vehicles-borrowing, car-sharing, renting, commuting out of town-rather than only whether they hold a title. This matters because non-owner eligibility depends on household vehicle access, not just ownership on paper. Independent agencies compare policies from multiple providers, and that ability to shop carriers is especially valuable for drivers with imperfect records or unusual coverage needs.
Key Car Insurance Benefits for Central Falls Drivers
-
Non-owner vs. owner policy guidance – We help Central Falls residents determine whether they qualify for a non-owner policy or need a standard auto policy based on owned vehicles, household vehicles, and regular access. Independent agencies can match policies to specific situations, so you get the kind of coverage that actually fits.
-
Local regulation expertise – Our guidance is grounded in Rhode Island law, including the minimum liability limits of 25/50/25 or $75,000 CSL from 230-RICR-20-05-3 and UM/UIM requirements from 230-RICR-20-05-1. Understanding these rules helps you avoid gaps in protection.
-
Support for drivers with imperfect records – Our team can often assist Central Falls drivers who have tickets, at-fault accidents, or lapses in coverage. We shop multiple carriers subject to underwriting, which means more options for drivers who might otherwise struggle to find a policy.
-
Clear explanations of liability, UM/UIM, and optional coverages – We provide plain-language breakdowns of terms like bodily injury, property damage, uninsured motorist, MedPay, comprehensive, and collision so you can make decisions with real understanding.
-
Practical focus on non-owners and occasional drivers – This guide and our approach are tailored to Central Falls drivers who may not own a car but still need to protect themselves and their loved ones when driving.
-
Easy ways to get started – Request quotes online at /car-insurance-quotes/ or call (844) 231-1313 to speak with a licensed professional about your Central Falls situation.
How Central Falls Car Insurance Works If You Don’t Own a Vehicle
Car insurance in Rhode Island is generally tied to the vehicle’s policy-the owner’s coverage is primary. But there are clear paths for a driver without a car to carry their own protection, and knowing which path fits you depends on a few specific factors.
Step 1: Look at the Vehicles in Your Household
Eligibility for non-owner policies in Central Falls is directly affected by whether you or anyone in your household owns a vehicle or has a car available for regular use.
“Regular use” means something specific in insurance terms: driving the same borrowed or household car multiple days a week, commuting with it, or having keys and open-ended permission to use it whenever you want. If this describes your situation, carriers will generally require you to be rated on that vehicle’s standard auto policy instead of issuing a separate non-owner policy.
When you contact RhodeIslandAutoInsurance.com, we’ll ask about all vehicles in your Central Falls household before recommending non-owner coverage. This step helps avoid eligibility problems at claim time.
Step 2: Decide If Non-Owner Car Insurance Fits You
A non-owner policy generally provides liability protection for an eligible named driver using vehicles they do not own. Household vehicles and vehicles available for regular use may be excluded. Check the actual policy terms and eligibility requirements before relying on it.
Non-owner policies typically provide liability coverage when you drive vehicles you don’t own, but they generally do not include collision or comprehensive for damage to the car you are driving. Coverage specifics depend on the insurer and the policy language.
Central Falls use cases where non-owner coverage often fits include:
-
Renting vehicles occasionally for work or travel
-
Borrowing a friend’s or relative’s car on an irregular basis
-
Maintaining continuous insurance history while between vehicles
-
Reviewing coverage before returning to driving after a suspension
For readers who want broader context on managing costs responsibly, our cheap car insurance page provides general strategies-but remember that non-owner eligibility has specific rules that go beyond price.
Step 3: Know When You Need a Standard Auto Policy Instead
A standard Rhode Island auto policy is typically required when you own a vehicle registered to a Central Falls address or when you have regular access to a household vehicle.
Common situations that call for a standard policy:
-
You finance or lease a car (the lienholder will almost always require comprehensive and collision). Full coverage may be necessary for financed or high market value vehicles.
-
You’re a co-owner on a vehicle title
-
You move into a household where a vehicle is regularly available to you
People often outgrow non-owner status as soon as a vehicle becomes part of their household. Insurance needs change over time, and your coverage approach must change with them. Major changes like buying a home or starting a business can also affect the kinds of insurance protection you need. Before you buy, sell, or start regularly using a new vehicle, reviewing your situation with our agency can help you avoid gaps.
Central Falls RI and Rhode Island Minimum Car Insurance Requirements
State law-not the city-sets minimum auto liability limits, but every Central Falls driver is expected to comply when insuring a vehicle. Rhode Island’s minimum liability requirements under 230-RICR-20-05-3 are:
-
$25,000 bodily injury liability per person
-
$50,000 bodily injury liability per accident
-
$25,000 property damage liability per accident
-
Or a $75,000 combined single limit (CSL) as an alternative
These limits apply to both standard and non-owner policies when purchased at state minimum levels. State minimum coverage is often the cheapest option for purchasing insurance, but these are legal minimums, not necessarily recommended limits-especially for Central Falls drivers who commute into denser traffic areas in Rhode Island or Massachusetts.
For a deeper breakdown of what minimum coverage includes and where it may fall short, visit our minimum car insurance page.
Uninsured and Underinsured Motorist (UM/UIM) Rules in Rhode Island
UM/UIM coverage helps protect you and your passengers if you’re hurt by a driver who has no insurance or not enough insurance. It does not protect the other driver-it protects you.
Under 230-RICR-20-05-1, Rhode Island requires insurers to offer UM/UIM bodily injury coverage with every personal auto policy. The rejection and reduction rules work as follows:
-
Full rejection of UM/UIM bodily injury coverage is only permitted when your liability limits are at the state minimum level, and the rejection must be in writing.
-
If you choose liability limits higher than the minimum, you may reduce UM/UIM bodily injury limits down to the statutory minimum, but you cannot reject it completely.
Insurers must also offer Uninsured Motorist Property Damage (UMPD) of at least $25,000. If collision coverage is present, written rejection of UMPD is not required; if collision is not included, UMPD applies at minimum unless you reject it in writing.
Central Falls drivers should think carefully before rejecting or reducing UM/UIM. This coverage protects you and your family-not other drivers-and the value of that protection increases when driving in areas with higher uninsured motorist rates.
Comparing Central Falls Car Insurance Options: Non-Owner vs. Standard Policy
Choosing between a non-owner policy and a standard auto policy depends on your vehicle access, how often you drive, and what you need covered. The table below provides a general comparison. Actual policies vary by insurer and underwriting; comparing insurance quotes requires identical liability limits and deductibles to make a fair assessment.
At-a-Glance Comparison Table
|
Feature |
Non-Owner Car Insurance (Central Falls) |
Standard Auto Policy (Central Falls) |
|---|---|---|
|
Who it’s for |
Licensed drivers without a car or regular access to a household vehicle |
Drivers who own, lease, or regularly use a vehicle |
|
Typical use |
Occasional rentals, infrequent borrowing |
Daily commuting, household use, regular driving |
|
Liability coverage |
Bodily injury and property damage liability, subject to RI minimums (25/50/25 or $75K CSL) |
Same liability structure with more coverage add-on options |
|
Damage to the car you drive |
Generally not included (no collision or comprehensive for the vehicle) |
Collision and comprehensive available if selected |
|
Eligibility limitations |
Cannot have owned or regularly available household vehicles |
Required when you own or have regular access to a vehicle |
|
Impact on continuous insurance history |
Maintains a continuous record while between vehicles |
Standard way to maintain continuous coverage |
|
UM/UIM and MedPay options |
UM/UIM generally available per RI law; MedPay may be offered depending on insurer |
UM/UIM required to be offered; MedPay optional per insurer |
RhodeIslandAutoInsurance.com helps Central Falls drivers choose the structure that best fits how they actually use vehicles. Drivers must compare quotes from multiple insurance providers for the best rates, and our agency streamlines that process.
Key Coverages Central Falls Drivers Should Understand
Understanding core coverages helps you choose more than just the cheapest option. Here’s what each type of coverage does and why it matters.
Liability Coverage in Central Falls
Bodily injury liability pays for injuries you cause to others in an accident. Property damage liability covers damage you cause to another person’s vehicle or property. Rhode Island’s minimums are 25/50/25, meaning $25,000 per person for bodily injury, $50,000 per accident, and $25,000 for property damage.
Consider a practical example: you borrow a friend’s car and cause a crash on a Central Falls street that injures a pedestrian and damages a parked vehicle. The liability portion of the applicable policy responds to those claims. If the costs exceed the policy limits, you could be personally responsible for the difference. Many drivers choose limits higher than the minimum to protect their income, savings, and assets.
Uninsured / Underinsured Motorist Coverage (UM/UIM)
UM/UIM protects you and your passengers if you’re injured by a driver who carries no insurance or insufficient coverage. It does not cover the at-fault driver-it covers you. Under 230-RICR-20-05-1, Rhode Island insurers must offer this coverage, and rejection or reduction follows the specific rules outlined above. Central Falls drivers, especially non-owners who ride with others or borrow different vehicles, should consider the financial impact of being hit by an uninsured driver.
Medical Payments Coverage (MedPay)
Rhode Island does not use a no-fault PIP system for personal auto policies. However, drivers may optionally add Medical Payments coverage, which can help pay initial medical bills for you and your passengers after a covered accident, regardless of who was at fault. MedPay is optional, and availability and limits depend on the insurer. It can be a practical addition for drivers who want some medical expense protection built into their auto policy.
Comprehensive and Collision (for Standard Auto Policies)
Comprehensive coverage may help with certain non-collision losses, such as theft, vandalism, or weather damage. Collision can help repair or replace your own vehicle after a covered crash, subject to your deductible. These coverage types are generally not part of non-owner policies because there is no specific insured vehicle. Lenders typically require both comprehensive and collision on financed vehicles registered in Central Falls.
Rental Cars, Borrowed Vehicles, and Central Falls Drivers
Central Falls drivers who don’t own cars often rely on rental cars or borrowed vehicles. How coverage works in these situations depends on the specific auto policy, the rental agreement, and Rhode Island law.
Driving a Friend’s or Family Member’s Car in Central Falls
In many cases, the vehicle owner’s Rhode Island auto policy is primary for liability when you have their permission to drive. But policy terms control exactly who qualifies as a covered driver and under what conditions.
If you drive the same borrowed car regularly-such as a roommate’s or partner’s vehicle-you may need to be listed on that policy instead of relying on non-owner coverage. Non-owner policies may exclude vehicles owned by household members even when you borrow them only occasionally. Open communication with the vehicle owner and an insurance professional is important before you become a frequent driver of someone else’s car.
Central Falls Drivers and Rental Car Liability
Personal auto policies in Rhode Island may extend certain liability coverage to qualifying rental vehicles when the insured rents a private passenger car. Under R.I. Gen. Laws § 27-7-6, qualifying private passenger automobile policies can provide property damage liability coverage for a rented motor vehicle (under 10,000 lbs) for up to 60 consecutive days.
It’s important to distinguish between:
-
Liability coverage – addressing injuries or damage you may cause to others while using the rental
-
Damage to the rental vehicle itself – which may or may not be covered by your auto policy; rental companies often sell separate damage waivers for the car itself
Non-owner policies typically focus on liability and usually do not pay for damage to the rental car itself, though policy language controls. Whether a non-owner policy qualifies as a “private passenger automobile policy” under § 27-7-6 is a separate legal question-Rhode Island courts have addressed this, and the answer is not always yes. Review your policy and rental agreement carefully, and ask about coverage details when getting a quote through our agency.
How to Get Central Falls Car Insurance Quotes Through a Trusted Insurance Agency Like RhodeIslandAutoInsurance.com
Comparing options is often the most effective way for non-owners and occasional drivers in Central Falls to find suitable coverage. They help avoid overpaying for insurance coverage while making sure protection needs are met.
Step 1: Gather Your Central Falls Information
Have the following ready before requesting a quote:
-
Full name, Central Falls address, and date of birth
-
Driver’s license number and state of issue
-
Driving history, including any tickets or accidents in recent years
-
Details on any vehicles you own or regularly use in your household
-
Whether you currently have insurance or have had a lapse
Accuracy matters. Carriers rate policies based on the information you provide, and discrepancies discovered later can affect claims.
Step 2: Decide What Type of Policy You’re Requesting
Think about whether you are:
-
A non-owner who borrows cars occasionally
-
Someone who rents vehicles frequently for work or travel
-
An owner or co-owner of a vehicle registered in Rhode Island
Our agency uses these answers to determine whether non-owner coverage is appropriate or a standard policy is required. Independent agencies offer personalized service tailored to client needs, and this step is where that tailoring begins.
Step 3: Compare Limit and Deductible Choices
You can usually choose liability limits higher than 25/50/25 or $75,000 CSL. Higher limits provide more protection for your assets but may come with a higher premium. For standard policies, choosing collision and comprehensive deductibles involves a similar trade-off between out-of-pocket costs at claim time and ongoing premium. For non-owner policies, the main decisions involve selecting liability and optional UM/UIM and MedPay limits.
Insurance companies offer discounts for safe driving and bundling policies, and some insurance providers utilize telematics to decrease rates for safe drivers. Multi-policy discounts may also be available through local agencies. Discuss your budget and protection goals with us so we can find a practical balance.
Local Context: Central Falls, the DMV, and Your Driver’s License
Being properly licensed and keeping your address information current is an important part of managing auto insurance in Central Falls. RhodeIslandAutoInsurance.com is not the DMV or any government agency.
Rhode Island DMV and Central Falls Drivers
The Rhode Island Division of Motor Vehicles handles licensing, vehicle registration, and certain reinstatement processes for Central Falls residents. For up-to-date office locations, hours, and services, visit the official DMV locations and hours page.
Rhode Island no longer requires SR-22 filings for financial responsibility in typical auto insurance contexts. If you are regaining your license or reinstating after a suspension, contact our agency to explore available insurance options once you are eligible to drive.
Many insurers use credit-based scoring for rates. A solid credit history may lower your premiums, and improving your credit score can lead to better rates over time. These are factors worth considering as part of your overall financial planning in Central Falls.
Central Falls Within the RhodeIslandAutoInsurance.com Service Area
Central Falls is one of many Rhode Island cities served by our agency, but this guide is tailored specifically to Central Falls residents and households. For information about other Rhode Island locations, visit our cities page.
While rates and eligibility vary by driver and insurer, our goal is to provide clear guidance for Central Falls drivers-with or without vehicles. Reviewing coverage annually helps avoid gaps in protection. A policy that worked two years ago may leave gaps today, and regular reviews can prevent being underinsured or overpaying.
Who Central Falls Non-Owner and Occasional-Driver Coverage Is For
Non-owner and liability-focused coverage serves a range of Central Falls residents. Here are the profiles we see most often.
Common Central Falls Driver Profiles
-
City commuters without a car – Central Falls residents who take transit or carpool most days but rent cars for trips or emergencies. A non-owner policy can provide liability protection during those occasional drives.
-
Young adults between vehicles – Drivers who sold a car, are saving for another, and want to maintain continuous insurance history. Non-owner coverage fills that gap without the cost of insuring a vehicle you don’t have.
-
Households sharing a single vehicle – Families where only one person is the titled owner, but another adult occasionally borrows the car. Household-vehicle exclusions may apply even to occasional borrowing; ask the insurer whether you need to be listed on the household policy.
-
Drivers rebuilding after tickets or accidents – Central Falls drivers working to keep consistent coverage while they improve their record. Our agency can shop carriers willing to underwrite these situations.
-
Caregivers and helpers – People who occasionally drive someone else’s vehicle to help loved ones with errands or medical appointments. Frequency of use determines whether non-owner or a listing on the vehicle owner’s policy is the right match.
Not every profile qualifies for a non-owner policy. If you have regular access to a household vehicle, a standard policy listing is usually the correct path.
Pricing and Budgeting for Central Falls Car Insurance
We cannot quote specific prices in this guide, but understanding what influences premiums helps you prepare for the quoting process.
Factors That Influence Your Premium
-
Driving record – Tickets, at-fault accidents, and suspensions are major rating factors for any policy type
-
Coverage limits – Higher liability and UM/UIM limits generally increase premium but improve protection
-
Vehicle type and usage (standard policies) – Commute distance, annual mileage, and vehicle value affect cost
-
Frequency and location of driving (non-owner policies) – How often you drive and where you drive matters
-
Prior insurance history – Lapses in coverage can increase rates; maintaining continuous coverage-even with a non-owner policy-helps
-
Credit-based factors – Where permitted, some carriers consider credit-based information in rating
For general strategies on managing car insurance costs in Rhode Island, our resource page offers practical guidance. The goal is always to find the right balance between value and protection-not simply the lowest price.
Frequently Asked Questions About Central Falls Car Insurance
Do I need car insurance if I live in Central Falls but don’t own a car?
Rhode Island law requires insurance on registered vehicles, not on people. If you truly don’t own or regularly use a vehicle, you are not legally required to buy a policy. However, if you drive at all-borrowing or renting-non-owner insurance may provide added liability protection that the vehicle owner’s policy alone might not fully cover.
Can I get non-owner car insurance if someone in my Central Falls household has a car?
Many insurers will not issue non-owner policies when a household member owns a vehicle that is available for your regular use. If you have regular access to a household car, you likely need to be added to that vehicle’s policy. Contact our agency to discuss the details of your situation so we can determine the right approach.
Does non-owner insurance cover damage to a rental car in Rhode Island?
Non-owner policies are typically designed for liability coverage and generally do not pay for damage to the rental car itself, though policy language controls. Liability for injuries or damage you cause to others may be addressed under the policy. Rental companies often sell separate damage waivers for the vehicle itself. Rhode Island statute § 27-7-6 applies to qualifying private passenger automobile policies for rental vehicle coverage, but whether a non-owner policy meets that statutory definition is a separate legal question.
Will every accident raise my Central Falls car insurance rates?
Not necessarily. Insurers evaluate fault, severity, claim type, and their own rating rules when deciding whether to adjust premiums. Not every claim results in an increase. Report claims promptly and ask your agent how a specific claim might affect future premiums.
What if I only drive a few times a year-do I still need my own policy?
If you always drive fully insured vehicles with the owner’s permission, you may rely on their policy. But that approach can leave gaps-especially if the owner’s limits are low or their policy excludes certain drivers. Frequent renters or those who borrow various vehicles throughout the year may want a non-owner policy to maintain their own liability protection and continuous coverage record.
How do I start a quote for Central Falls car insurance?
Central Falls residents can request quotes online at /car-insurance-quotes/ or call (844) 231-1313. Have your Central Falls address, license information, driving history, and household vehicle details ready. Quote requests do not bind insurance coverage legally-coverage begins only when binding and the effective date are confirmed.
Get Central Falls Car Insurance Help Today
Whether you’re a non-owner who borrows a car once a month, an occasional renter, or someone ready to insure a vehicle for the first time, understanding where you stand under Rhode Island law is the foundation for making good coverage decisions. The minimum liability rules, UM/UIM requirements, and non-owner eligibility standards outlined above all shape what kind of policy fits your life in Central Falls.
An independent agency like RhodeIslandAutoInsurance.com can compare options across multiple carriers, explain the trade-offs in plain language, and help you find coverage that matches how you actually use vehicles. Our agents are ready to work through your specific situation-no obligation, no pressure.
-
Request a Central Falls–focused quote at /car-insurance-quotes/
-
Call (844) 231-1313 to speak with a licensed professional about your needs
Requesting information does not obligate you to purchase. Review the actual policy documents before making any coverage decisions, and reach out whenever your situation changes-because the right policy today may not be the right policy next year.